How I learned to stop worrying and love my kidney stone
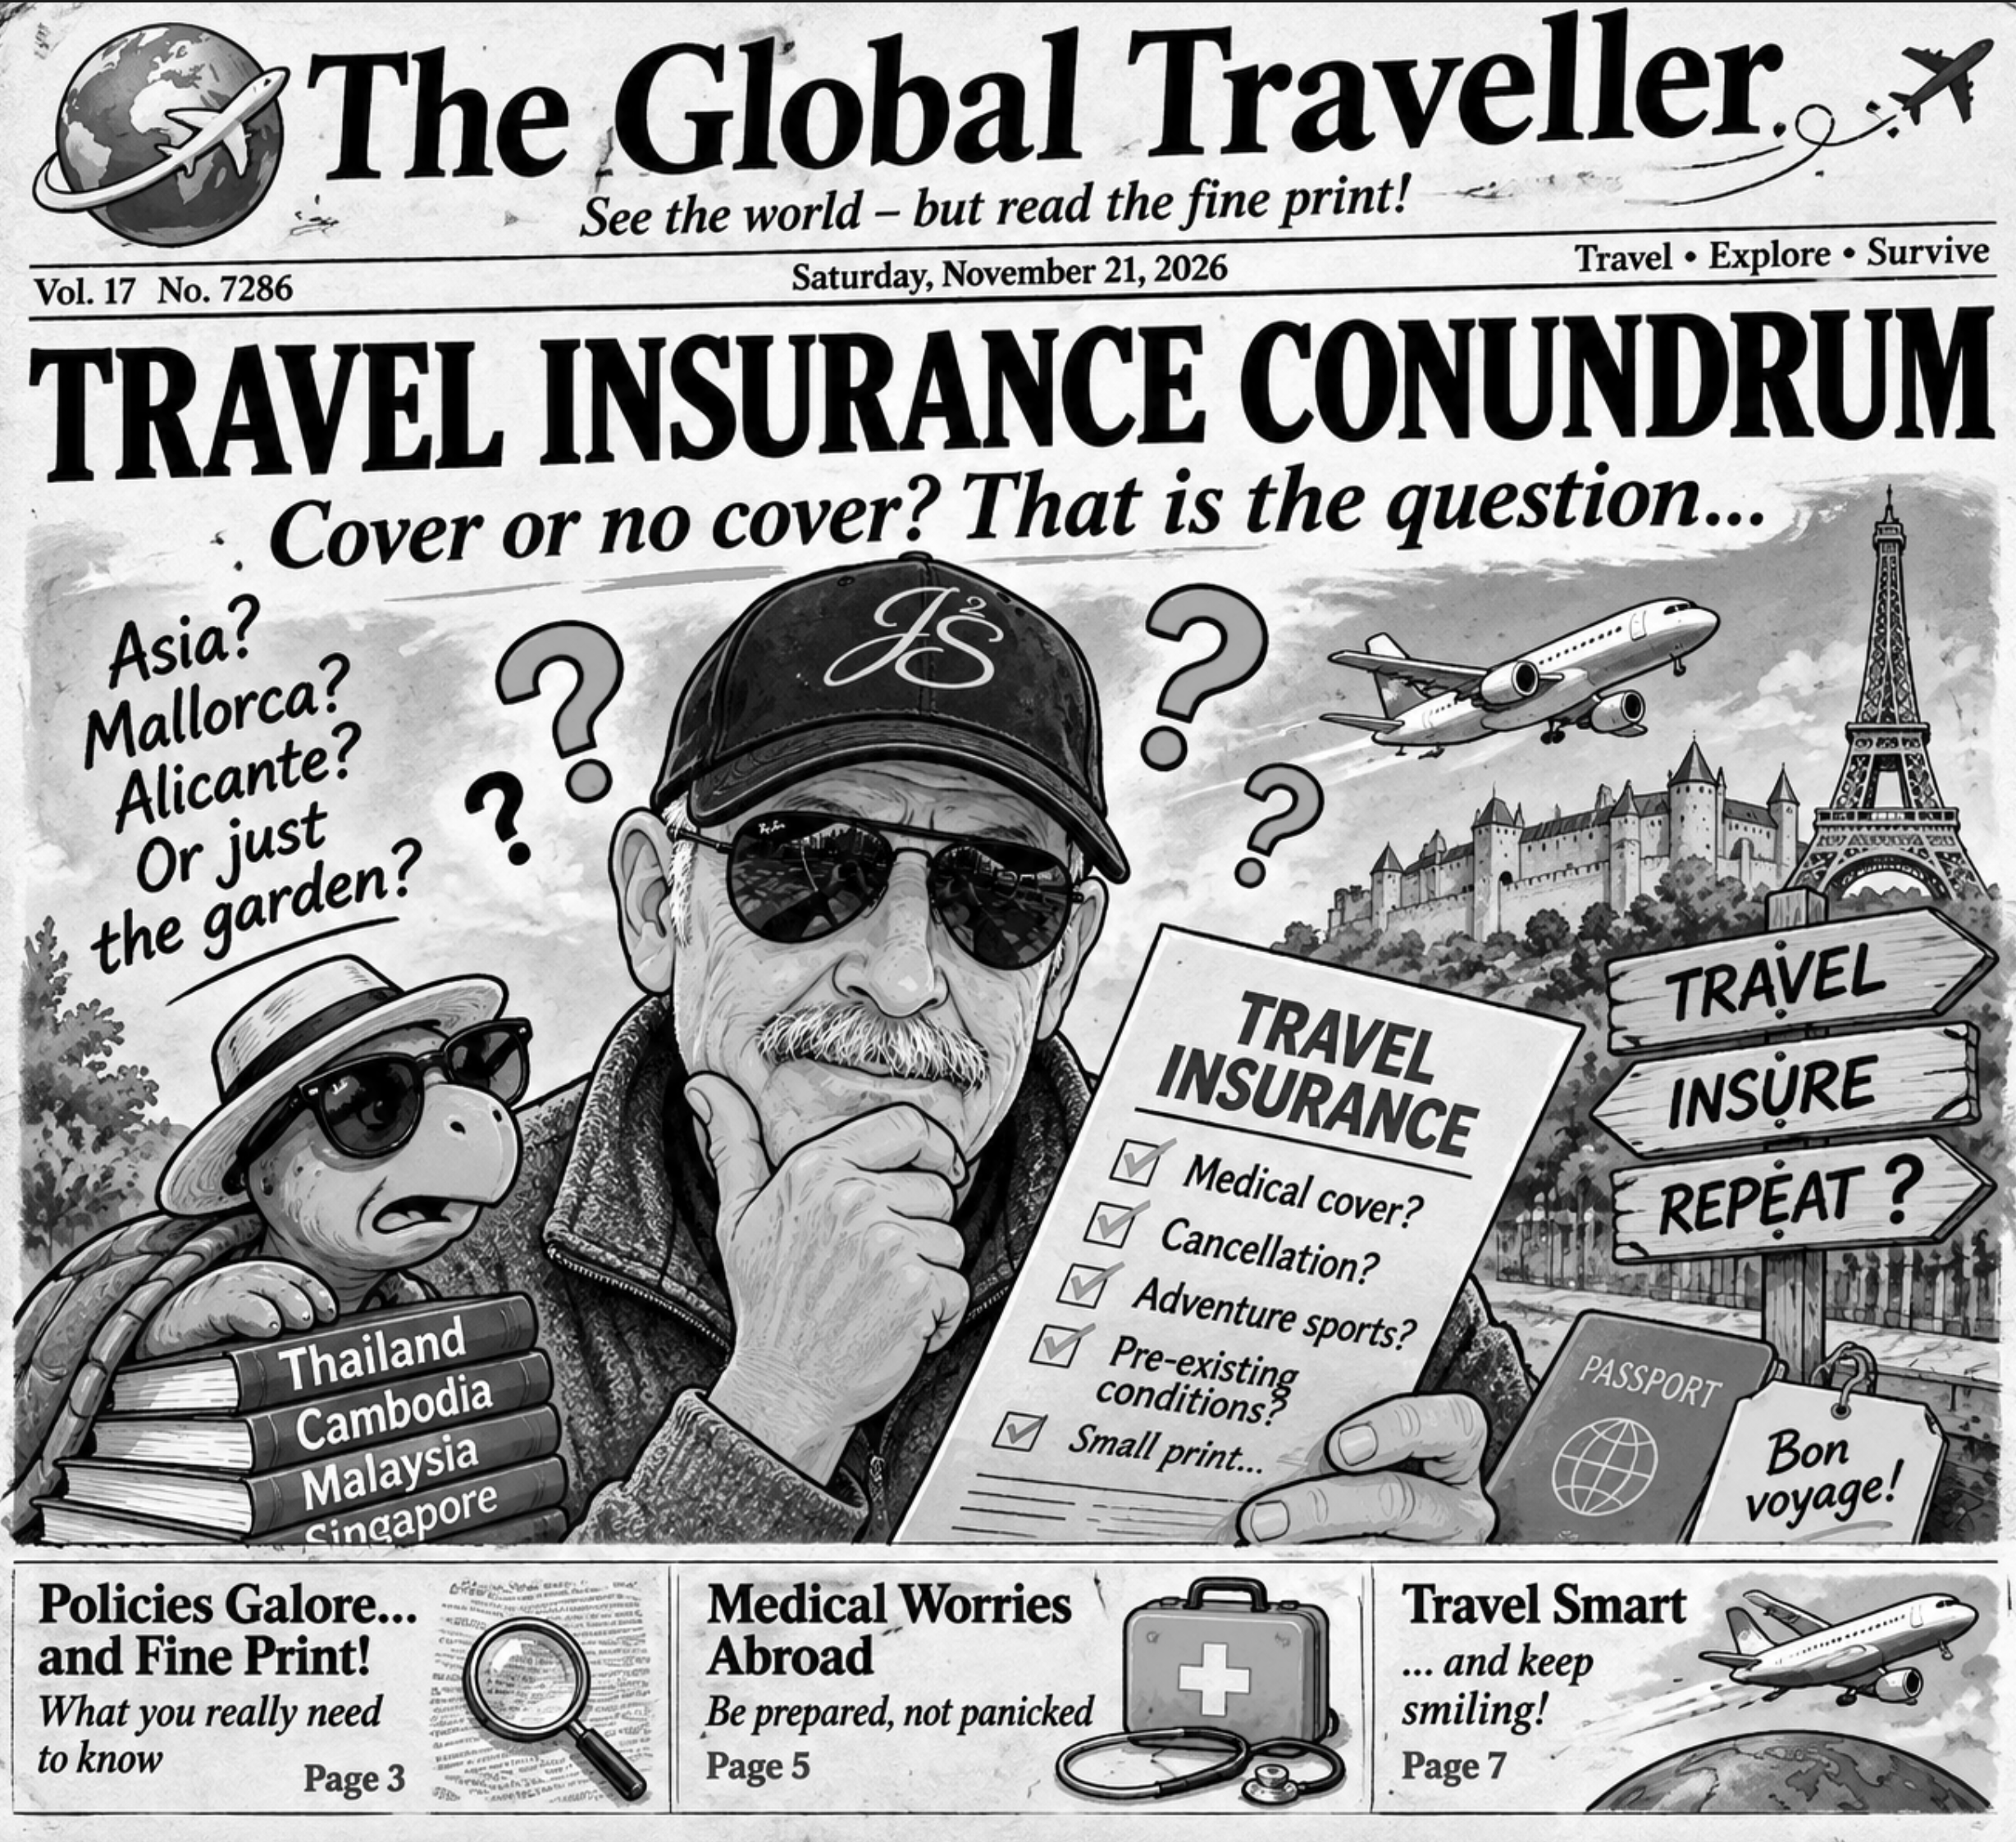
In a month, we’ll be trading the grey drizzle of home for the sticky, noodle-scented chaos of South East Asia. Naturally, it’s far too early to think about packing. I’ll be doing that the night before, in a blind panic, like a civilised adult.
It is, however, the perfect time to sort out visas and travel insurance. One of these is a form-filling exercise. The other is a psychological thriller.
✏️ The Questionnaire
Every insurer opens with the same friendly question: “Have you had any medical conditions in the past three months?”
Why three months? Who decided that? Is there a secret Council of Actuaries somewhere, in a dimly lit room, deciding that your body’s behaviour from 91 days ago is deeply relevant, but day 92 is ancient history, a mere rumour? “Ah yes, your appendix. Fine. We’ll allow the appendix. But the hiccups in September? Premium doubled.”
✏️ Enter the Stone
My situation, for those who haven’t been following my body’s little melodrama, is this: I have a kidney stone. It hasn’t left. It has, in fact, unpacked its bags, put its feet up and started receiving mail.
I assumed that a stone still in residence might be a minor footnote. Wrong. Apparently it counts as a “pre-existing condition”, which in insurance language translates to “we’d love to cover you, as long as you’d love to pay ten times the price.”
Ten times! For a pebble! I’ve seen smaller premiums on a Ferrari.
✏️ The Hopeful Theory
I’m choosing to believe it will pass naturally before departure. It’s a lovely thought: the stone, sensing my financial distress, quietly packing up and moving out with dignity. I’d even throw it a leaving party.
Realistically, I suspect it’s more like a stubborn tenant who’s discovered rent control and has no plans to leave before March.
✏️ The Options
- Declare it honestly, pay the extortionate premium, and fund the insurer’s next team-building retreat.
- “Forget” to mention it, which is a fabulous plan right up until you need to claim for a kidney stone in a Bangkok hospital, at which point the insurer discovers it’s been a long-term resident. Don’t do this. I’m only listing it so you can admire how bad an idea it is.
- Wait and hope. The stone leaves, I tick “no”, everyone’s happy. Trouble is, the policy window is closing faster than my patience.
- Shop around for a specialist insurer who covers pre-existing conditions without charging a ransom. Not glamorous, but probably the grown-up answer.
✏️ The Verdict (Pending)
I’m leaning towards option 4, with a generous side order of option 3 and a prayer to whichever deity oversees urinary tracts.
If you have recommendations for insurers who don’t treat a kidney stone like a hostage situation, please drop them in the comments. Or, indeed, any stone-passing tips. Hydration, I’m told. Lots of it. So if my next post is mostly about the best toilets in Thailand, you’ll know how it went.
Stay tuned. And drink water. 💧
Return to Mission Control


